房子住了些年,市值涨上去了,手上那笔房贷利率又还不错——这时候要装修、要给孩子交学费、或者小生意周转,很多湾区业主会被建议:“别动原来那笔房贷,加一条 HELOC 就行。”
于是文件包送来了,签约当天公证员上门。你翻开那一叠纸,发现它跟当年买房时签的东西既像又不像:也有一份信托契据要公证,也有一份”三天撤销权”的通知书,可通知书上写的条文号却和你印象里的不一样。
这篇文章不重复讲贷款签约的通用流程——那些在《重新贷款、卖房签约时,公证员到底在做什么》里已经写过。这里只讲 HELOC 与它们不同的那几处,尤其是最容易被写错、也最容易被讲错的一处:撤销权。
HELOC 借的是一条额度,不是一笔钱
先把三个容易混淆的东西分开。
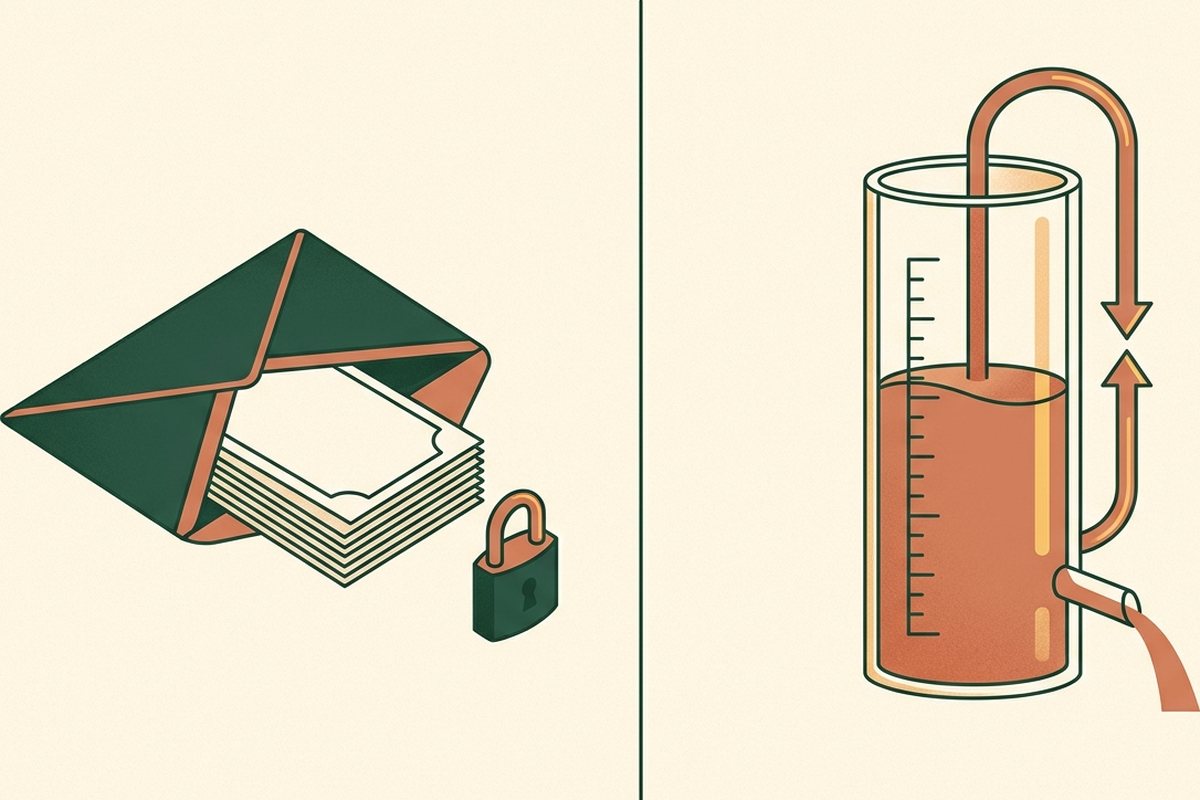
重新贷款(refinance),是把原来那笔房贷换成一笔新的房贷:金额、利率、期限重新定,旧的还清、新的接上,你手上仍然只有一笔按月还的贷款。
房屋净值贷款(home equity loan),按消费者金融保护局(CFPB)的说法,是”a specific amount of money borrowed against the equity of your home”——一次性拿到一笔钱,之后按期还。
HELOC(Home Equity Line of Credit,房屋净值信用额度)则是第三种东西。CFPB 把它形容成”a line of credit, like a credit card, except you are borrowing against the equity of your home”:批下来的是一个额度上限,你可以在上限之内多次提取(borrow or draw money multiple times),而且还进去多少,可用额度就恢复多少。
这个”可循环”的性质,带来了 HELOC 独有的两个阶段:
- 提取期(draw period)。CFPB 的解释是,你可以在这段”借款期”内随时用到额度上限。这段时间里你可能只还很少的钱,甚至只还利息——具体怎么算,看你签的那份合同。
- 还款期(repayment period)。提取期一结束,你就不能再从 HELOC 提款了,随即进入还款期。CFPB 特意提醒了一句值得抄下来的话:“Monthly payments are often significantly higher once you enter repayment.”(进入还款期之后,月供往往会明显变高。)
具体的提取期和还款期各有多长、利率怎么浮动、有没有最低提取额,各家贷款方各不相同,也会随时间变化,本文不给数字——这些正是你要在披露文件里逐项看清、并当面问贷款经纪的内容。
还有一件事值得先知道:额度批下来,不等于随时一定取得到。CFPB 提醒,如果房屋价值明显下跌,贷款方可能决定不再允许你在这条 HELOC 计划下继续动用信用;你的财务状况发生变化、贷款方认为你还不上时,也可能冻结你继续提款的能力。
还有一句话必须放在这一节的末尾。CFPB 在解释 HELOC 时写得很直白:还不上、或者跟不上还款进度,“you could lose your home”——房子是可能保不住的。这句话不是修辞,它正好引出下一节:HELOC 之所以能有那样的额度,是因为它拿你的房子作了担保。
它照样在你的房子上设担保,所以照样要公证、要登记
不少人以为,HELOC 是”银行给的一个额度”,比按揭轻,随便签签就好。恰恰相反:从担保和登记的角度看,它和一笔房贷没有本质区别。
法律要求贷款方在申请阶段就把这件事讲清楚。Z 条例(Regulation Z)专门为房屋净值计划设了一条第 1026.40 条,其中第 (d)(3) 款要求披露文件里必须有一句声明:贷款方将在消费者的住所上取得担保权益,且违约时可能失去该住所(“A statement that the creditor will acquire a security interest in the consumer’s dwelling and that loss of the dwelling may occur in the event of default.”)。
在加州,这个”担保权益”落到纸面上,通常就是一份信托契据(Deed of Trust)——和买房、重贷时那份是同一类文件,只是这一份担保的是你的 HELOC。它要送到县登记处(County Recorder)登记,而登记的前提,是加州《政府法典》第 27287 条那句话:除少数例外,“before an instrument can be recorded its execution shall be acknowledged by the person executing it”——文件在能够被登记之前,签署须由签署人办理签名确认(acknowledgment),并按法律规定出具证词。
所以公证员出现在 HELOC 签约桌上,理由和重贷时一模一样:不是为了让文件”更有分量”,而是因为不公证就登记不进去,登记不进去,贷款方的担保就不成立,钱也就不会放。
两个与房产文件绑定的细节,在 HELOC 签约时同样适用:
- 要按右手拇指指纹。《政府法典》第 8206 条第 (a)(2)(G) 款规定,需公证的文件若是”deed, quitclaim deed, deed of trust, or other document affecting real property”或授权委托书,公证员必须要求签署人在登记簿上按右手拇指印。HELOC 的信托契据正落在这一类里。这是法定动作,不是公证员多事。
- 公证员证的只是”你签了字”。加州《民法典》第 1189 条规定的签名确认证词,开头就印着一句法定免责声明:“A notary public or other officer completing this certificate verifies only the identity of the individual who signed the document…, and not the truthfulness, accuracy, or validity of that document.”——只核验签名人的身份,不担保文件内容的真实、准确或有效。同一条证词里还有 “personally appeared” 一语,这正是你本人必须到场的法律来源。
如果你名下已经有一笔房贷,那么按 CFPB 的归类,房屋净值贷款和 HELOC 都会被视为”second mortgages”——第二顺位的房贷,要在原来那笔之外另行偿还。顺位是贷款方之间的事,与公证无关;但它解释了为什么这份契据同样一份都不能少。
(如果你要办的不是贷款,而是家人之间加名字、把房子转进信托这类单独办理的过户契据,另见《房产过户契据(Grant Deed / Quitclaim Deed)公证》。)
撤销权:HELOC 适用的是另一条法条
“美国贷款签完还有三天可以反悔”这句话,在 HELOC 上确实成立——但依据的法条,和重新贷款那一条不是同一条。这一点在中文资料里常被写混,也是我们在签约桌上被问得最多的地方。
分界线是”闭合式”与”开放式”。 一笔金额固定、按期摊还的贷款(买房贷款、重新贷款、一次性的房屋净值贷款)属于闭合式信贷,撤销权规定在 Z 条例第 1026.23 条。而 HELOC 是一个可以反复提取、还款后额度恢复的计划(plan),属于开放式信贷(open-end credit)——CFPB 自己的消费者页面就把它定义为一条允许你反复借用房屋净值的”open-end”信用额度——撤销权因此规定在第 1026.15 条。两条的标题都叫 “Right of rescission”,条文措辞相近,内容却有实打实的差别。
下面把第 1026.15 条与 HELOC 有关的几处,逐条说清楚。
可以撤销的是”计划”,不是每一次提款
第 1026.15 条第 (a)(1) 款开宗明义:在一项以消费者主要居所(principal dwelling)作担保的信贷计划中,其所有权受该担保约束的每一位消费者,都有权撤销——
- 计划开立时的这个计划本身(the plan when the plan is opened);
- 为已有计划新增或提高担保时的那个担保权益(a security interest when added or increased to secure an existing plan);
- 信用额度被调高时的那部分增额;
- 以及计划项下的每一次授信。
但紧接着的第 (a)(1)(ii) 款把最后一项收了回去:消费者没有权利撤销计划项下的授信,只要该次授信是按已经确定的额度上限作出的(“in accordance with a previously established credit limit for the plan”)。
翻成人话:你有三天可以反悔的是”开立这条额度”这件事本身;日后在额度之内的每一次提款,不再各带一次三天撤销权。这是 HELOC 与一次性借款在撤销权上最实际的一处不同——签约那天的窗口,过了就是过了。
起算点与”营业日”
按第 (a)(3) 款,撤销期限算到”引发撤销权的那件事发生、第 (b) 款要求的通知书交付、全部重要披露文件交付”三者之中最晚一项之后的第三个营业日午夜。
这里的”营业日”是一个特别定义。Z 条例第 1026.2 条第 (a)(6) 款先给了通常含义,然后写道:“However, for purposes of rescission under §§ 1026.15 and 1026.23…”——明确把 1026.15 和 1026.23 并列点名——在这些情形下,营业日指除星期日和法定公众假日以外的所有日历日。也就是说,星期六照样算数。
第 (a)(3) 款还留了一条长尾:如果该给的通知书和重要披露没有交付,撤销权要到引发事件发生三年后、或你转让全部房产权益、或房产出售时(三者最先发生者)才失效。
通知书两份,撤销要书面
第 (b) 款要求贷款方向每一位有撤销权的消费者交付两份撤销权通知书,通知书上要写明担保权益、撤销权的内容、如何行使(并附一份可用的撤销表格与贷款方营业地址)、撤销的法律效果,以及撤销期届满的日期。
夫妻共有房产、配偶不是借款人的情形要特别留意:条文说的是”其所有权受该担保约束的每一位消费者”,因此配偶只要产权受这份担保约束,同样有撤销权、同样应当拿到两份通知书。签约当天人不在场,就只能另约时间补上。
行使撤销要用书面形式通知贷款方(“by mail, telegram, or other means of written communication”),并且以寄出、交电报、或送达贷款方指定营业地点之时为准。撤销不是向公证员行使的——公证员在这件事上的角色,只是把通知书交给你、请你在收据上签字。
一旦有效撤销,按第 (d) 款,引发撤销权的那个担保权益归于无效,消费者不承担任何金额(包括财务费用);贷款方须在收到撤销通知后 20 个日历日内返还已收取的款项或财物,并采取必要行动使该担保权益的终止得以体现。
两条法条的豁免清单不一样——这是最要紧的差别
第 1026.23 条第 (f) 款列了四种没有撤销权的情形,其中第 (2) 项是许多重贷客户熟悉的那一条:“A refinancing or consolidation by the same creditor of an extension of credit already secured by the consumer’s principal dwelling.”——由同一贷款方对已以主要居所作担保的债务所作的重新贷款或债务合并。
而适用于 HELOC 的第 1026.15 条第 (f) 款,整份清单只有两项:
- 住宅按揭交易(a residential mortgage transaction);
- 以州政府机构为债权人的信贷计划(a credit plan in which a state agency is a creditor)。
没有”同一贷款方”这一项。这意味着:在你现有房贷的那家银行开立一条 HELOC,条文本身并没有把它排除在撤销权之外——这与”在原贷款方那里做纯降息重贷通常没有撤销权”的直觉正好相反。
至于第 1 项的”住宅按揭交易”,第 1026.2 条第 (a)(24) 款的定义是:为”取得或初次建造该住所”提供融资而在消费者主要居所上设定或保留的担保交易。所以,买房交割时与首笔房贷同步开立、用于支付购房款的那种 HELOC(俗称 piggyback),落在这条豁免里;而房子买下来若干年后再开的 HELOC,不属于这一类。
最后一条例外要知道但不必主动去用:第 (e) 款允许消费者在”确有真实的个人财务紧急情况”(bona fide personal financial emergency)时修改或放弃撤销权,但必须由全体有撤销权的消费者签署一份注明日期、说明紧急情况、明确放弃或修改该权利的书面声明,且明文禁止使用印制的格式表格。有人递给你一张印好的弃权表让你签,这本身就该让你停下来。
不确定自己这条 HELOC 有没有撤销权、几号到期?答案写在你手里那份通知书上——它必须载明撤销期届满的日期。看不到、或者上面的日期与你的理解不符,请当场问贷款方,而不是问公证员:这个问题不在公证员的职责范围之内。
签约那天,桌上会有哪些文件
HELOC 的文件包通常比买房那一摞薄,但结构清楚,大致分成四类。各家贷款方的名称和份数不尽相同,以你收到的文件清单为准。
一、信贷协议(HELOC Agreement / Credit Agreement)。这是额度本身的合同:额度上限、提取期与还款期怎么划分、利率怎么定与怎么浮动、最低还款怎么算、有哪些费用。它是整包文件里最该慢慢读的一份,但通常并不需要公证——公证与否取决于文件要不要送去登记,而不是取决于它重不重要。
二、信托契据(Deed of Trust)。上一节说过:要公证、要按右手拇指印、要送县登记处登记。签约当天真正需要公证员到场的,主要就是它。
三、撤销权通知书(Notice of Right to Cancel)。每位有撤销权的人两份,你签的通常是”已收到”的回执,而不是撤销本身。它不需要公证,但请当场确认三件事:份数对不对、名字有没有漏人、上面那个届满日期是哪一天。
四、披露文件(Disclosures)。这一类里最该被认真对待的,是 Z 条例第 1026.40 条要求的那一套。它的交付时点写得很明确:这些披露和小册子应当在向消费者提供申请表时一并提供(“shall be provided at the time an application is provided to the consumer”)——也就是申请阶段,不是签约当天。其中第 (d)(5) 款要求写明计划的付款条件,并且提取期与还款期若适用不同的付款条件,披露必须分别反映;第 (e) 款还要求提供一本名为《What You Should Know About Home Equity Lines of Credit》的房屋净值小册子(或适当的替代物)。
如果你手上从来没见过这两样东西,那不是签约当天该补的,而是该在签约之前向贷款方索取的。
此外,文件包里往往还会有身份与住址类的声明、占用声明、签名样本、错误与遗漏更正条款(compliance agreement)等等。这些多数只需签字,个别可能需要公证,看文件上有没有附公证证词的空白页——有证词页的就要公证,没有的就不要,这一点由出具文件的一方决定,公证员不能替你添也不能替你减。
公证员在这一桌上的位置
HELOC 签约里,公证员做的还是那三件事:核验身份、见证签署或主持宣誓、出具证词并登记在册。同样,有几件事一定不做:
- 不解释你的额度、利率或还款条件。这些属于贷款方与贷款经纪的职责;由公证员来讲,既超出法定职权,也踩到公证员不得提供法律意见的红线。相关红线我们在《公证员不能做什么》里逐条列过。
- 不替你判断这笔 HELOC 划不划算、该不该签。
- 不替你选公证类型。是办签名确认(acknowledgment)还是宣誓书公证(jurat),由文件上的证词页决定。
- 不替你填空。哪一格填什么、哪一项勾哪个,得你自己决定或问贷款经纪。
证件问题请务必提前对一遍。加州对可接受证件有一份法定清单,中国护照在列、美国绿卡不在;贷款方按信用报告上的写法印全名,护照上却只有拼音,两边对不上就得改期。详见《公证时带什么证件》。发现名字对不上,请在签约前几天告诉贷款经纪,而不是等公证员上门那一刻。
公证费本身有法定上限,上门交通费另计、必须分开报价,完整算法见《加州公证收费是多少》。HELOC 签约里,这笔钱通常由贷款方或签约调度公司结算,你一般不必当场付现。
签约之前,把这几件事问清楚
- 向贷款方要齐第 1026.40 条要求的申请阶段披露与那本小册子,在签约之前读,而不是签约当天读。
- 确认提取期与还款期的分界,以及进入还款期后月供会怎么变。CFPB 那句”往往会明显变高”,值得你要一份具体的测算。
- 确认产权上的每一个人是否都要签、都要到场。配偶不是借款人但产权受担保约束的,撤销权与到场要求同样落在他/她身上。
- 提前核对证件与英文姓名拼写,不一致就先联系贷款经纪更正,别等签约当天。
- 签约时数一数撤销权通知书的份数,并把届满日期抄进日历。要撤销就书面通知贷款方,打电话或跑一趟不算数。
- 想清楚一件事:这条额度是拿你的房子担保的。用不用得着、什么时候用、用多少,主动权在你手里;但担保从额度开立那天起就已经登记在案了。
参考来源与查证记录9 条
以下来源均于引用当日打开核对;条目中的”查证于”日期为实际核对日期,可点击的日期指向互联网档案馆(Wayback Machine)当时的存档快照。
- 联邦《诚实借贷法》Z 条例第 1026.15 条(开放式信贷的撤销权,HELOC 适用)— CFPB 规章原文。第 (a)(1)(i) 款:“Except as provided in paragraph (a)(1)(ii) of this section, in a credit plan in which a security interest is or will be retained or acquired in a consumer’s principal dwelling, each consumer whose ownership interest is or will be subject to the security interest shall have the right to rescind: each credit extension made under the plan; the plan when the plan is opened; a security interest when added or increased to secure an existing plan; and the increase when a credit limit on the plan is increased.”;第 (a)(1)(ii) 款:“…the consumer does not have the right to rescind each credit extension made under the plan if such extension is made in accordance with a previously established credit limit for the plan.”;第 (a)(2) 款:“To exercise the right to rescind, the consumer shall notify the creditor of the rescission by mail, telegram, or other means of written communication.”;第 (a)(3) 款:“The consumer may exercise the right to rescind until midnight of the third business day following the occurrence described in paragraph (a)(1) of this section that gave rise to the right of rescission, delivery of the notice required by paragraph (b) of this section, or delivery of all material disclosures, whichever occurs last.”,及”the right to rescind shall expire 3 years after the occurrence giving rise to the right of rescission…”;第 (b) 款:“a creditor shall deliver two copies of the notice of the right to rescind to each consumer entitled to rescind”,并要求披露”The date the rescission period expires.”;第 (d)(1) 款:“the security interest giving rise to the right of rescission becomes void”;第 (d)(2) 款:“Within 20 calendar days after receipt of a notice of rescission, the creditor shall return any money or property…”;第 (e) 款:“The consumer may modify or waive the right to rescind if the consumer determines that the extension of credit is needed to meet a bona fide personal financial emergency… Printed forms for this purpose are prohibited.”;第 (f) 款豁免仅两项:“A residential mortgage transaction.” 与 “A credit plan in which a state agency is a creditor.” — 查证于 2026-08-31
- Z 条例第 1026.23 条(闭合式信贷的撤销权,用于对比)— CFPB 规章原文。第 (a)(1) 款:“In a credit transaction in which a security interest is or will be retained or acquired in a consumer’s principal dwelling…except for transactions described in paragraph (f) of this section.”;第 (f) 款豁免共四项,其中第 (2) 项:“A refinancing or consolidation by the same creditor of an extension of credit already secured by the consumer’s principal dwelling.”——此项在第 1026.15 条的豁免清单中并无对应条款。 — 查证于 2026-08-31
- Z 条例第 1026.40 条(房屋净值计划/HELOC 的披露要求)— CFPB 规章原文。第 (b) 款:“The disclosures and brochure required by paragraphs (d) and (e) of this section shall be provided at the time an application is provided to the consumer.”;第 (d)(3) 款:“A statement that the creditor will acquire a security interest in the consumer’s dwelling and that loss of the dwelling may occur in the event of default.”;第 (d)(5) 款:“The payment terms of the plan. If different payment terms may apply to the draw and any repayment period, or if different payment terms may apply within either period, the disclosures shall reflect the different payment terms.”;第 (e) 款:“The home equity brochure entitled ‘What You Should Know About Home Equity Lines of Credit’ or a suitable substitute shall be provided.” — 查证于 2026-08-31
- Z 条例第 1026.2 条(定义)— CFPB 规章原文。第 (a)(6) 款”business day”:”…However, for purposes of rescission under §§ 1026.15 and 1026.23, and for purposes of §§ 1026.19(a)(1)(ii)… the term means all calendar days except Sundays and the legal public holidays specified in 5 U.S.C. 6103(a)…”;第 (a)(24) 款”residential mortgage transaction”:“A transaction in which a mortgage, deed of trust… is created or retained in the consumer’s principal dwelling to finance the acquisition or initial construction of that dwelling.” — 查证于 2026-08-31
- CFPB 消费者问答 — 《什么是房屋净值信用额度(HELOC)?》。支持句:“A home equity line of credit (HELOC) is an “open-end” line of credit that allows you to borrow repeatedly against your home equity.”;“If you get a HELOC, you can generally spend up to your credit limit anytime during the borrowing period, also called the “draw period.””;“After the draw period ends, you stop being able to borrow from your HELOC and enter the “repayment period.””;“Monthly payments are often significantly higher once you enter repayment.”;“If the value of your home decreases significantly, your lender might decide not to allow you to take out additional credit under your HELOC plan”;“If you fall behind or can’t repay the loan on schedule, you could lose your home.” — 查证于 2026-08-31
- CFPB 消费者问答 — 《房屋净值贷款与房屋净值信用额度(HELOC)有什么区别?》。支持句:“A home equity loan is a specific amount of money borrowed against the equity of your home.”;“A Home Equity Line of Credit (HELOC) is a line of credit, like a credit card, except you are borrowing against the equity of your home.”;“…these new loans would be considered second mortgages that you’d need to pay in addition to your first mortgage.”;“With a Home Equity Line of Credit (HELOC), you can borrow or draw money multiple times from an available maximum amount.”;“when you make payments on your HELOC the amount of available credit is replenished.” — 查证于 2026-08-31
- 加州《政府法典》第 27287 条(文件登记前须经签名确认)— leginfo 法条原文。支持句:“…before an instrument can be recorded its execution shall be acknowledged by the person executing it… and the acknowledgment or proof certified as prescribed by law.”;条文列举的例外情形不含普通的信托契据(deed of trust)。 — 查证于 2026-08-31
- 加州《政府法典》第 8206 条(登记簿与右手拇指指纹)— leginfo 法条原文。第 (a)(2)(G) 款:“If the document to be notarized is a deed, quitclaim deed, deed of trust, or other document affecting real property, or a power of attorney document, the notary public shall require the party signing the document to place his or her right thumbprint in the journal.” — 查证于 2026-08-31
- 加州《民法典》第 1189 条(签名确认证词法定格式)— leginfo 法条原文。支持句:“A notary public or other officer completing this certificate verifies only the identity of the individual who signed the document to which this certificate is attached, and not the truthfulness, accuracy, or validity of that document.”;法定证词正文含 “personally appeared” 一语。 — 查证于 2026-08-31